September 24, 2026 7:33AM
How Far Ahead Do Malaysians Plan Their Finances?
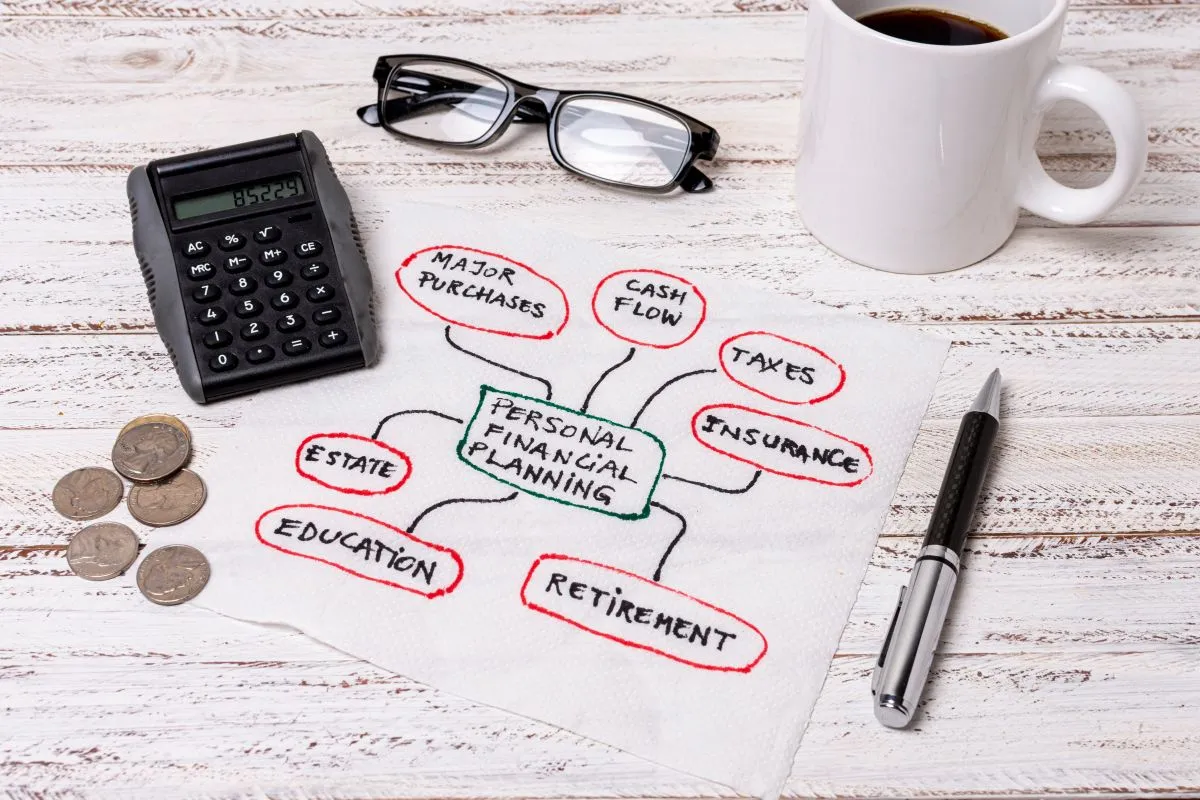
Financial planning is often associated with long-term goals such as retirement, property ownership and investing. But for many Malaysians, financial planning begins much closer to home: managing monthly expenses, keeping debt under control and finding enough room to save.
The Vodus Financial Wellbeing & Planning Study Malaysia 2026 shows that Malaysians are not disengaged from their finances. Many are budgeting, saving and trying to improve their financial position. The bigger challenge is that immediate commitments can keep attention focused on the near term, leaving less room to prepare for emergencies and longer-term goals.
Understanding how far ahead Malaysians plan therefore tells us more than whether they have a financial plan. It reveals how much financial breathing room households have to move from managing today to preparing for tomorrow.
Research Methodology
This article is based on the Financial Wellbeing & Planning Study Malaysia 2026 conducted by Vodus Research. The study surveyed 1,947 Malaysian adults nationwide, with respondents stratified to reflect the Malaysian population. Fieldwork was conducted from 12 to 15 May 2026 using Vodus Research’s proprietary OMTOS online survey methodology.
The study examines Malaysians’ current spending situation, financial planning, money-management habits, savings, debt, investment readiness and overall financial progress.
Key Insights
- Malaysians plan their finances only 4.8 months ahead on average, while just 13% plan beyond one year. Among households with MHI above RM12,000, long-term planning rises to 27%.
- Planning further ahead does not automatically mean being more financially prepared. 63% of those planning 4–12 months ahead are financially on track, compared with 59% of those planning beyond a year and 56% of short-term planners.
- There is a clear gap between knowing what to do and feeling able to do it. While 65% know how to improve their financial future, only 51% say managing their money is relatively easy.
- Short-term planning does not necessarily mean impulsive spending. Although 68% of 18–24-year-olds are short-term financial planners, 57% of this age group say they would save and buy later when something is unaffordable.
Most Malaysians Are Planning Only a Few Months Ahead
The typical Malaysian financial plan does not extend very far into the future.
On average, Malaysians plan their finances 4.8 months ahead. Around 6 in 10 are short-term planners, while only 13% plan beyond one year.
The planning horizon also varies significantly across age and income groups. Short-term planning is particularly common among 18–24-year-olds and households with MHI below RM5,000, both at 68%. By comparison, 27% of households with MHI above RM12,000 are long-term planners, more than twice the overall level.
This does not necessarily mean Malaysians are failing to plan. For households managing recurring bills, food, transport and other commitments, planning several months ahead can itself require considerable financial discipline.
The challenge emerges when that planning horizon is too short to accommodate financial needs that require years rather than months, such as retirement, property ownership or long-term investing.
Financial Stability Comes Before Long-Term Wealth Building
Why are financial planning horizons relatively short? One reason can be found in what households are prioritising.
Daily expenses are the main financial priority for 31% of Malaysians, followed by growing savings at 20% and paying off debt at 14%. Emergency funds account for another 10%. In comparison, only 5% identify investing for future growth as their main priority, another 5% prioritise retirement and 3% focus on buying a home or property.
Life stage also shapes these priorities. Daily expenses are particularly important among 45–54-year-olds at 39%, while 26% of Malaysians aged 18–24 prioritise growing their savings, above the 20% overall figure.
The broader picture is not necessarily one of poor financial ambition. Instead, many households appear to be working through the fundamentals of financial stability before they can give more attention to wealth building.
Someone focused on monthly expenses, savings or debt repayment may recognise the importance of investing and retirement planning. But these longer-term goals become harder to prioritise when current financial commitments require more immediate attention.
Planning Further Ahead Does Not Automatically Mean Greater Readiness
It may seem logical that Malaysians who plan furthest ahead should also feel the most financially prepared. The study suggests the relationship is more complicated.
Among Malaysians who plan less than three months ahead, 56% say they are financially on track. This increases to 63% among those planning four to 12 months ahead but stands at 59% among people planning beyond one year.
The finding suggests that simply extending a financial plan further into the future does not necessarily create stronger readiness.
A practical medium-term plan may work particularly well when it is connected to achievable actions such as saving regularly, managing debt or preparing for upcoming expenses. Longer-term planning remains important, especially for retirement and wealth building, but a distant goal provides limited financial security if households do not have the resources or habits to act on it today.
The more important question may therefore be not only how far ahead Malaysians plan, but how effectively they can translate those plans into action.
Financial Room Makes Plans Easier to Act On
The ability to follow through on a financial plan is closely connected to how much financial room a household has.
Overall, 60% of Malaysians describe themselves as either making progress or prepared and on track. Another 19% are trying to plan but doing so inconsistently, while 21% are either unprepared or primarily focused on current needs.
Income creates a particularly clear divide. Among households with MHI above RM12,000, 78% are financially on track. Being unprepared is more common among households with MHI below RM5,000 at 30%, while Malaysians aged 45 and above also show a higher incidence of being unprepared at 35%.
The relationship becomes even clearer when households are grouped according to their current spending situation.
Among Malaysians who feel comfortable with their spending, 80% are financially on track. This falls to 64% among worried spenders, 60% among cautious savers, 43% among those managing necessities only and just 23% among Malaysians with very limited money.
Financial planning therefore does not happen independently of financial circumstances. More breathing room gives households greater ability to move beyond immediate commitments and convert financial intentions into consistent action.
Malaysians Often Know What to Do, but Acting on It Is Harder
One of the more revealing findings in the study is the gap between financial knowledge and practical financial control.
Around 6 in 10 Malaysians say they can prepare their own monthly budget, follow their financial plans and manage their use of credit. 65% say they know what to do to improve their financial future.
Yet only 51% say they have little or no difficulty managing their money.
Here too, income matters. Among households with MHI above RM12,000, 73% say they have little or no difficulty managing their money, compared with 51% overall. Financial-management confidence is also generally stronger among Malaysians with degree or postgraduate qualifications.
The divide becomes even sharper when households are grouped by their spending situation. Managing money feels relatively easy for 81% of comfortable households, compared with only 27% of constrained households.
This points to an important distinction in financial wellbeing. Knowing how to budget, save or plan does not necessarily mean a household has sufficient capacity to do so consistently.
Financial education remains important, but knowledge alone cannot create additional disposable income, deepen an emergency buffer or make monthly commitments easier to manage.
Short-Term Planning Does Not Mean Malaysians Are Spending Impulsively
A short financial planning horizon could easily be interpreted as evidence of short-term thinking. Malaysians’ behaviour when faced with an unaffordable purchase suggests otherwise.
In 2026, 47% say they would save and buy the item later, up from 35% in 2025. Meanwhile, the proportion who would simply not make the purchase fell from 45% to 30%.
Only 23% would buy immediately using another mechanism such as BNPL or instalments, credit cards, borrowing or another source of cash.
Younger Malaysians provide an especially interesting contrast. 68% of 18–24-year-olds are short-term financial planners, yet 57% of the same age group say they would save and buy later when something is unaffordable.
This suggests that planning only a few months ahead should not automatically be interpreted as a lack of financial discipline. Younger Malaysians may have shorter planning horizons while still being willing to delay gratification when affordability is tight.
The same save-and-buy-later behaviour is also particularly common among households with MHI of RM12,000 to RM16,000 at 57%. By comparison, deciding not to buy at all is more common among Malaysians aged 55 and above at 45% and households earning above RM16,000 at 37%.
For businesses and brands, this has an important implication. Affordability pressure may not always remove purchase intent. In some cases, it simply pushes the purchase further into the future.
Financial Planning Needs to Start with Where Households Are Today
The findings show that Malaysians are already taking steps to manage their finances. They are budgeting, prioritising savings, delaying purchases and thinking about how to improve their financial position.
But there is no single financial-planning journey.
Younger and lower-income Malaysians are more likely to plan close to the present, while higher-income households have greater scope to plan further ahead. At the same time, the findings show that a longer planning horizon by itself does not guarantee stronger financial readiness.
What appears to matter is the combination of planning, financial capacity and the ability to act consistently.
For financial institutions, policymakers and employers, this means support should reflect where households are in their financial journey. Those facing greater financial pressure may first need practical help with budgeting, cash flow, debt and emergency savings. Households with stronger financial capacity may be better positioned for retirement planning, investing and longer-term wealth building.
Helping Malaysians plan further ahead therefore requires more than encouraging them to think about the future. It requires helping households turn future goals into practical financial steps they can realistically take today.
Explore the Full Financial Wellbeing & Planning Study Malaysia 2026
The full Financial Wellbeing & Planning Study Malaysia 2026 provides a deeper view of how Malaysians manage their finances, how financially prepared they feel and where opportunities exist to strengthen household resilience. The report covers:
- Spending and financial pressure
- How Malaysians feel about their current spending situation and how financial pressure differs across groups.
- Financial planning and priorities
- Planning horizons, financial goals and differences across age, income and other profiles.
- Money-management behaviour.
- Budgeting, financial discipline, credit management and behaviour when affordability is tight.
- Savings and emergency readiness
- Monthly savings rates, emergency buffers, six-month coverage and retirement preparedness.
- Debt and repayment confidence
- Long-term debt levels, debt manageability and how repayment pressure varies across households.
- Investment readiness and participation
- Investment knowledge, spare cash, barriers to getting started and the investment assets Malaysians hold.
- Financial progress and confidence
- Whether Malaysians feel they are moving forward and how confident they are about achieving their financial goals.
- Financial support needs
- Where Malaysians want help with budgeting, savings, emergencies, debt, investing and retirement planning.
The findings are further analysed across demographic and financial profiles, helping organisations understand which Malaysians face greater financial pressure, which groups are ready to move forward and where different forms of financial support may be most relevant.
Vodus Research is a market research company in Malaysia providing consumer and B2B research to help organisations understand customers, evaluate market opportunities and make better business decisions. Using our proprietary OMTOS online survey methodology and nationwide consumer reach, we deliver fast, actionable market research in Malaysia across a wide range of industries.
Our market research solutions include consumer research, target market research, brand health tracking, product and concept testing, customer satisfaction surveys, advertising research and B2B market research. We help businesses uncover consumer behaviour, measure brand performance, identify growth opportunities, improve customer experience and strengthen marketing effectiveness.